• Getting ready to apply for a mortgage?

    Getting ready to apply for a mortgage?

    Mortgage Application Ready? Your Document Checklist
    Pay Stubs Ready: Gather your recent pay stubs so your income can be reviewed as part of the mortgage application.
    W-2s Included: Add your W-2s to help document employment income for the mortgage application.
    Bank Statements: Prepare your bank statements to document available funds and support a complete application.

    Continue to full article
  • Your credit score is more than just a number, it can play an important role in your mortgage options and the interest rate you may qualify for.

    Your credit score is more than just a number, it can play an important role in your mortgage options and the interest rate you may qualify for.

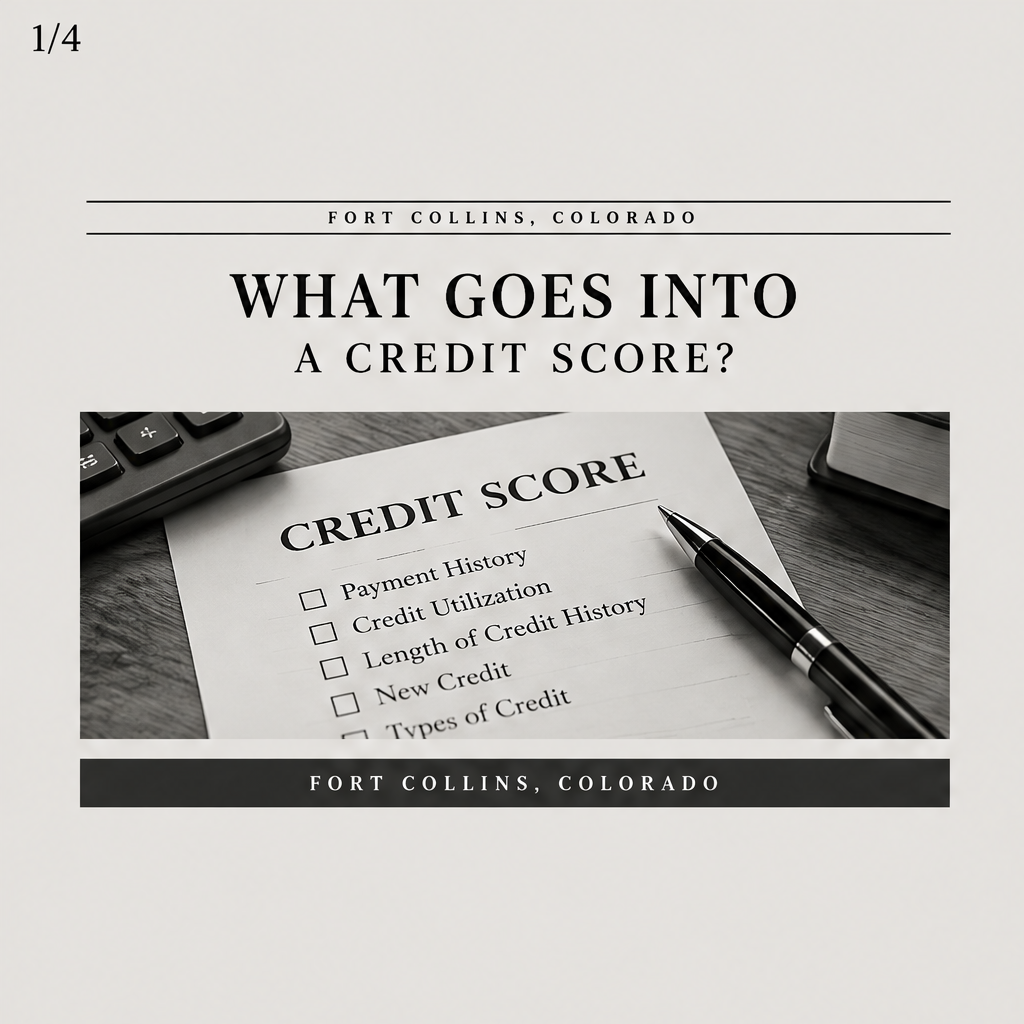
    What Goes Into a Credit Score?
    Payment history matters: On-time payments can support your credit profile, while late payments may affect it and your future mortgage planning.
    Credit use counts: Your balances compared with your available limits can influence your score, so review revolving-account utilization before a mortgage application.
    Keep applications intentional: New credit inquiries and account age can affect scoring, so discuss planned mortgage credit activity with your broker.

    Continue to full article

  • Mortgage Preapproval Beats Basic Prequalification

    Prequalification gives buyers an early borrowing estimate using basic financial details and a soft credit check that should not affect credit scores.
    Preapproval goes deeper: buyers complete an application, provide financial documents, and let the lender verify credit, income, and qualifications before shopping seriously.
    A preapproval letter can show loan amount, interest rate, and key terms, helping buyers compare lenders and prepare stronger offers with confidence.
    Sellers may want to see prequalification before next steps, but preapproval gives more specific details when buyers are ready to act quickly.
    Prequalification is not required, and it is not guaranteed. Seek preapproval only when ready because letters usually last 60 to 90 days.

  • One of the best parts of calling Northern Colorado home is having places like Horsetooth Reservoir just west of Fort Collins.

    One of the best parts of calling Northern Colorado home is having places like Horsetooth Reservoir just west of Fort Collins.

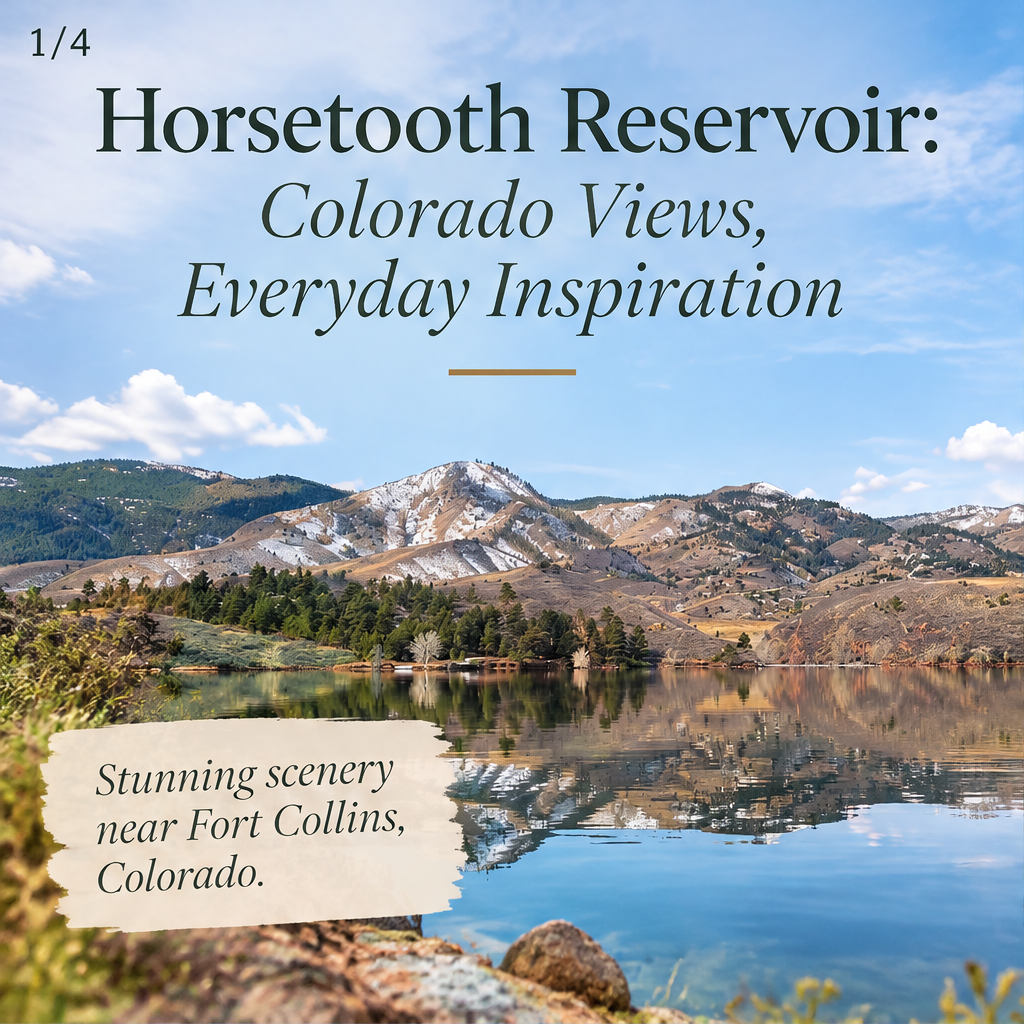
    Horsetooth Reservoir: Colorado Views, Everyday Inspiration
    Scenic surroundings: Horsetooth Reservoir pairs reflective water, mountain views, trees, and open skies. An inspiring setting to keep in mind when imagining life near Fort Collins, Colorado.
    Outdoor perspective: The photos show shoreline access, people on the water, and a path leading toward the reservoir, highlighting how a nearby natural setting can enrich your homeownership vision.
    Explore your next step: Use Horsetooth Reservoir’s beauty as inspiration while considering what location, surroundings, and daily experiences matter most in a home near Fort Collins, Colorado.

    Continue to full article

  • A little about me!

    A little about me!

    Meet Your Loan Officer: A Clearer Path to Your Next Home
    Start with clarity. I explain the lending process, answer questions, and help you understand the steps involved in pursuing a home loan.
    Expect direct communication. We can discuss your goals, review relevant details, and identify the information needed to move forward.
    Take the next step. Reach out to begin a conversation with your loan officer about your home-financing questions.

    Continue to full article

  • Homeowners Look Beyond the Rate

    Rate lock-in can become a trap when homeowners focus only on interest rates, instead of weighing total cost, equity, cash flow, and long-term goals.
    Staying put may fit some owners, while others may benefit from moving despite a higher rate, depending on their full finances.
    The process starts with reviewing equity, retirement exposure, and debt, then matching needs with options like a HELOC, second mortgage, bridge loan, or reverse mortgage.
    Non-QM choices can also expand flexibility for self-employed borrowers and Real Estate investors who need financing structures beyond standard loan options and guidelines.
    The main takeaway: educate first, compare alternatives, and choose housing financing that supports affordability, flexibility, responsible equity access, and long-term life goals.

  • 2026 First-Time Buyers Need Savings Strategy

    First-time buyers need more than a deposit: closing costs, moving expenses, insurance, taxes, lender fees, and repairs all belong in the plan.
    2026 may offer decent opportunities for stable, prepared buyers, with 30-yr fixed mortgages in the low-6% range and easing forecast ahead this yr.
    A buyer's market can expand choices and strengthen negotiation, especially when inventory exceeds demand and fewer buyers compete for similar nearby homes.
    Saving ~20% remains a common target; conventional loans require 620 credit scores, while government-backed options may allow 580, or lower with larger deposits.
    Pre-approval helps buyers set a realistic range before house hunting, and emergency savings help manage urgent repairs while building habits for future purchases.

  • Buying a home involves several steps, but knowing what to expect can make the process feel much more manageable.

    Buying a home involves several steps, but knowing what to expect can make the process feel much more manageable.

    Mortgage 101: Your Path to Closing
    1. Get pre-approved. Share the requested financial information with a lender to understand your borrowing range before home shopping.
    2. Choose a home and submit an offer. Once your offer is accepted, provide the lender with the property details needed to continue the loan process.
    3. Review and close. Complete the lender’s remaining requirements, review the closing documents, and sign when ready to finalize the purchase.

    Continue to full article

  • Make Your Mortgage Work for Your Goals 🏡

    Mortgage options differ widely, so compare loan type, down payment needs, credit standards, interest structure, and total long-term cost before choosing carefully.
    Conventional loans can offer flexibility, but buyers with <20% down typically face private mortgage insurance and strict credit qualification standards from lenders.
    Government-insured, military-backed, and rural housing loans may fit different borrowers, including lower down payments, eligible service benefits, or rural/suburban projects depending on eligibility.
    Refinancing replaces an existing mortgage, often to adjust payments, shorten from 30-yr to 15-yr terms, switch loan types, or access cash strategically.
    Home equity loans and HELOCs let owners borrow against built-up value for improvements, consolidation, or major expenses, while weighing collateral responsibility carefully.